Taxes
Year-End Tax Planning: 12 Moves to Make Before Dec. 31
Year-end tax planning for 2026: Roth conversions, RMDs, charitable gifts, and the 0% capital gains rate retirees can still use before Dec. 31.
The personal finance articles in this section cover taxes, financial wellness, retirement planning, the use of financial advisors, and estate planning.
Financial planning and personal finance are undertakings where you adopt habits today so that you are better off in the future. To effectively manage your money, you need to set goals and make the right financial decisions today with regards to your spending, income, and savings so that you are set up for whatever the future holds.
Maintaining a personal financial plan is meant to be a part of your life like eating well and getting exercise. However, managing money is not as well integrated into as many people’s routines as physical fitness – even though the research shows that people with written plans feel more confident and have less stress.
Plans enable you to make better decisions, develop better financial habits, and have improved financial outcomes.
Year-end tax planning for 2026: Roth conversions, RMDs, charitable gifts, and the 0% capital gains rate retirees can still use before Dec. 31.
Long-term capital gains are taxed at 0%, 15%, or 20%. See the 2026 and 2027 brackets by filing status and how other income pushes your rate higher.
See how much a tax-free Roth conversion can cover in 2026 and 2027, how the senior deduction adds room, and what can still cost you.
See the 2026 tax brackets for the return you file in 2027, plus the new 2027 brackets, standard deductions, and the extra deductions at 65 and older.
A market downturn lets you convert the same shares to a Roth for less taxable income. See the benefits, risks, and how much to convert in 2026 and 2027.
The 2026 midterms put Democrats in control of Congress. Here’s what that could mean for Social Security, taxes, healthcare, and Roth conversions.
Behavioral finance explains why smart people sell low, save too little for retirement, and claim Social Security early. Here are the biases and the fixes.
A Monte Carlo simulation tests your retirement plan across 1,000 simulated markets to estimate your odds. Here’s how it works and what your score means.
The net investment income tax adds 3.8% to investment income once MAGI tops $200,000 or $250,000. See who pays it, how it’s figured, and how to cut it.
The best asset allocation strategy for you today? As you age? Is age the best way to determine investment strategy? Get answers.
You can retire at 62 if savings cover your spending until Social Security and three years of health coverage. Here’s how to check the math.
People with a financial plan are more than twice as likely to feel confident. See what 2026 retirement surveys show and the planning steps people skip.
Homeowners 62+ hold a record $15.34 trillion in home equity. See 6 ways to use home equity in retirement, what each costs, and when it makes sense.
The average U.S. inheritance is about $125,000, and the median among heirs is $124,000. See figures from parents, trusts, wealth tiers, and estate tax limits.
Moneymaxxing, No Buy 2026, and soft saving lead this year’s personal finance trends. See what each one involves and which ones help your plan.
On October 15, 2026, the PlannerPlus price rises to $168 a year for new subscribers. Subscribe before then to get the current $144 price.
Ask any financial planner and the same three personal finance rules come up first. See them, then explore 22 more for building real wealth.
Retirement changes how money works: fewer earning years, more tax decisions. These 10 rules cover withdrawals, spending, and what shifts over time.
How to save for retirement: aim for about 15% of income, use accounts in the right order, and see 2026 401(k), IRA, and HSA limits plus ways to save more.
Financial mapping can lead you to better financial decisions and outcomes, turning scattered goals into a plan that holds up against risk.
Vanguard just paid billions for Altruist to scale advisors. Boldin’s CEO argues the bigger opportunity is scaling what you can do yourself.
Specific, research-backed ways to help you deal with financial stress and money worries. Start building real confidence today.
Poor financial decision making costs more than money. Learn to slow down, cut bias, and choose with a clear plan.
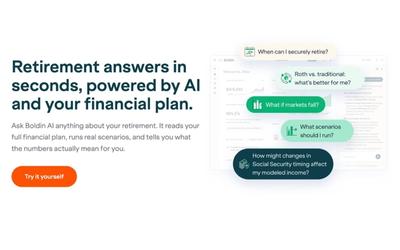
Ask Boldin AI about your plan, or tell it what changed to keep your plan current. You approve every update the AI makes before it’s applied.
Take financial wellness into your own hands and do it yourself retirement planning: easy, comprehensive, reliable.