Taxes
Year-End Tax Planning: 12 Moves to Make Before Dec. 31
Year-end tax planning for 2026: Roth conversions, RMDs, charitable gifts, and the 0% capital gains rate retirees can still use before Dec. 31.
How you invest, spend money, buy insurance, donate to charities, fund education, and more will impact how much you pay in taxes now, and into the future. Learn to minimize what you pay the government.
Make choices to save into the right savings vehicles. Opt for pre-tax savings (traditional, SEP & Simple IRAs, 401ks, 403bs, 457s, 529s, HSAs, etc…) where you don’t pay taxes on the money you invest until you withdraw the funds in the future or after-tax savings (Roth IRAs and 401ks) are when you save money that has already been taxed.
You also want to consider how you can manipulate both income and spending to optimize your tax bracket.
Year-end tax planning for 2026: Roth conversions, RMDs, charitable gifts, and the 0% capital gains rate retirees can still use before Dec. 31.
Long-term capital gains are taxed at 0%, 15%, or 20%. See the 2026 and 2027 brackets by filing status and how other income pushes your rate higher.
See how much a tax-free Roth conversion can cover in 2026 and 2027, how the senior deduction adds room, and what can still cost you.
See the 2026 tax brackets for the return you file in 2027, plus the new 2027 brackets, standard deductions, and the extra deductions at 65 and older.
A market downturn lets you convert the same shares to a Roth for less taxable income. See the benefits, risks, and how much to convert in 2026 and 2027.
Retirement tax planning comes down to which accounts you tap, when, and how much. Here are 9 strategies, updated for 2026 and the $6,000 senior deduction.
What to gather and what to check before you file your 2026 return, from the senior deduction and RMDs to Roth conversions, QCDs, and Form 8606.
The net investment income tax adds 3.8% to investment income once MAGI tops $200,000 or $250,000. See who pays it, how it’s figured, and how to cut it.
Up to 85% of your Social Security can face federal income tax, and 8 states tax it too. See the thresholds, the new senior deduction, and 2027 earnings limits.
Your RMD age is 73 or 75, depending on birth year. These 6 RMD strategies, from QCDs to Roth conversions, can lower the taxes on your withdrawals.
Give up to $111,000 from your IRA tax-free with a QCD in 2026. See who qualifies, how it counts toward your RMD, and how to report it.
A Roth conversion can raise your Medicare premiums two years later. Every mistake on this list comes with a solution.
Nine states skip income tax, but property and sales taxes change the math. See how all 50 states tax Social Security, pensions, and IRA withdrawals.
Two CFP® professionals answer real questions on Roth conversion timing, the pro rata rule, and avoiding surprise Medicare or ACA costs.
The Big Beautiful Bill didn’t end taxes on Social Security. It added a $6,000 senior deduction through 2028. Here’s what changed for retirees.
We cover 8 creative tax strategies, plus the retirement planning approach that can save you more money.
After 50, you can contribute up to $32,500 to a 401(k) and $8,600 to an IRA in 2026. Here’s how catch-up limits work at every age.
Paying taxes in retirement means managing income streams, quarterly deadlines, and the IRS safe harbor, without an employer doing it for you.
Learn the pros and cons of different Roth conversion timing strategies and how to choose the right approach for your retirement plan.
See how the Boldin Planner applies the One Big Beautiful Bill Act: the higher standard deduction, $6,000 senior deduction, SALT cap, and permanent brackets.
Asset location is an important concept if you are trying to save and build wealth. Explore ways to locate funds to minimize taxes.
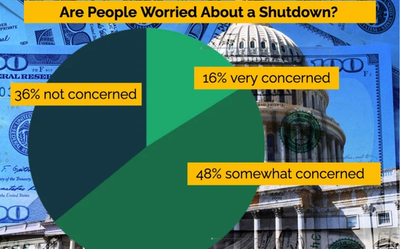
Boldin survey reveals most Americans worry a government shutdown and also the threat to ACA subsidies and retirement confidence.
Want to retire in your 50s and withdraw from savings? You need to understand the Roth 5 year rules to avoid penalties.
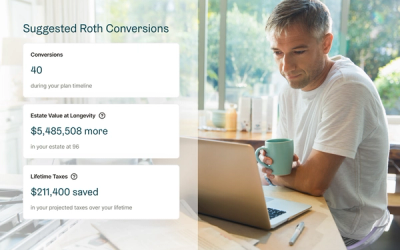
Roth conversions are a powerful tax planning strategy, but how do retirement savers actually use them? A recent survey of Boldin subscribers reveals that users…
Take financial wellness into your own hands and do it yourself retirement planning: easy, comprehensive, reliable.